

In 2025, Nigerian films outsold Hollywood at the cinema for the first time. The box office hit a record.
In the same year, filmmakers were quietly leaving cinemas for YouTube.
Both things are true, and the gap between them is the real story. Africa’s film industry does not have one business model. It has three, and each one rewards a different kind of producer.
Cinema: the biggest cheques, for the fewest people
The numbers are the best the industry has seen. FilmOne’s data put the 2025 box office across Nigeria, Ghana and Liberia at ₦15.6 billion, roughly 35% above 2024’s ₦11.58 billion. Nollywood took 49.4% of the market. Hollywood took 48.8%.
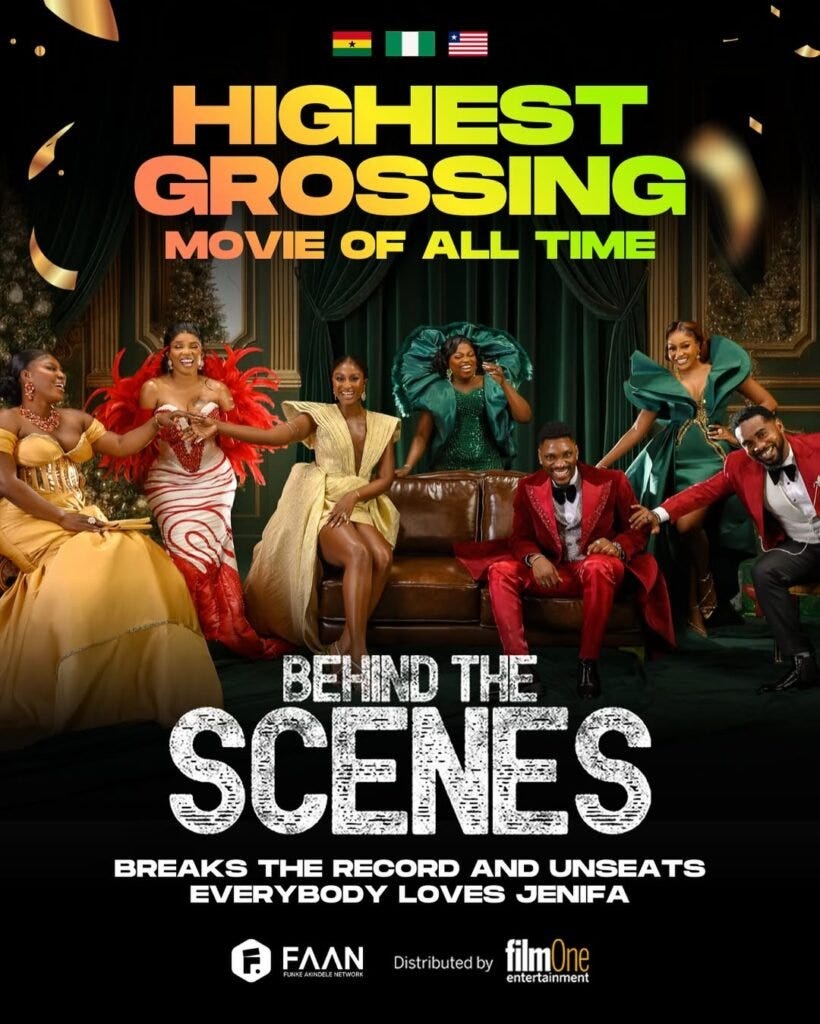
Behind the Scenes did what no YouTube film has done. FilmOne reported more than ₦2.1 billion within a month of its December release. One later estimate puts the gross nearer ₦2.76 billion.
But a gross is not a payout.
Before a producer sees a naira, the ticket money passes through taxes and the cinema. In the first week, producers and exhibitors typically split 50/50. In week two it moves to roughly 45/55. As a run goes on, the exhibitor’s share can climb toward 70%. Then the distributor takes its cut from the producer’s side, usually 15% to 20%.
One published model, which its author labels illustrative, runs the numbers on a ₦2.76 billion gross. After taxes, the exhibitor share and the distributor’s fee, the producer keeps around ₦990 million, or roughly 30% to 40% of gross. Treat that as a rule of thumb. Nobody publishes real deal terms.
Then there is the entry fee. A cinema-grade release can cost ₦250 million to ₦300 million, according to a BusinessDay editorial. You need a distributor, the distributor needs screens, and you get one window.
The scale is also smaller than the record suggests. The same editorial, citing FilmOne, put admissions across Anglophone West Africa at just over 2 million in 2025 by early December. A cinema outing for a Lagos family can cost ₦30,000 to ₦40,000. The cinema market is rich per ticket and thin per head.
Elsewhere, the model works where the habit is deep. Egypt’s cinema runs on its holidays. Barshama opened on the eve of Eid al-Fitr this year and took EGP 23.2 million in a single day, reported as the highest daily gross in Egyptian cinema history. Cinema pays at that scale when audiences go together, on a schedule.
Where the habit is not deep, it struggles. Ghana has no comprehensive system for tracking box office results, and its cinemas cluster in a few cities. Kenya has lost cinemas in central Nairobi, and its local films compete for a small share of screens.
Streaming: the register that is closing
Streaming promised a way around cinema’s gatekeepers. It brought its own.
Platforms pick a small number of titles and pay a flat licence fee. A 2021 account, based on producers speaking off the record, put Nollywood fees at about $10,000 to $90,000, with most deals near the middle. The 2025 estimate for the 2 to 3 year licence window is lower: roughly $10,000 to $50,000 from the big platforms, and $5,000 to $30,000 from African-owned ones. Predictable, but capped, however well the film does.
And the buyers are retreating. Techpoint reports that Netflix and Amazon Prime have cut African content spending. In Kenya, Showmax ended in April 2026 after commissioning around 30 Kenyan originals in five years. Its shows moved to a pricier service, and viewers were still reporting missing titles months later.
Being on a platform is not the same as being found. Several well-regarded Kenyan titles sat within subscribers’ reach and never entered the wider conversation.
YouTube: open to everyone, paid by the view
YouTube is the only register with no gate. Upload, and you are in.
That is why it now dominates how many Nigerian films are released. A 2026 NPR report found filmmakers using it as their primary platform. Love in Every Word passed 30 million views. One channel passed 169 million views in just over a year.
And the cost structure is the point. A strong YouTube title runs ₦9 million to ₦15 million, against ₦250 million or more for a cinema push. A producer can shoot in four days and release within weeks.
The break-even maths is useful. A ₦10 million film needs about 10 to 12 million organic views within 30 to 60 days to recover its cost. That is under ₦1 per view. Top titles reach 1 to 5 million views, so most films do not clear that bar on their own. New channels often lose money on their first four or five uploads, because the algorithm favours established ones.
The per-view rate is the constraint. Techpoint puts typical CPMs for African creators at $0.30 to $1.50, against $5 to $10 or more in Western markets. One estimate places earnings anywhere from about $470 to $12,000 per million views, depending on audience mix. Channels with strong diaspora audiences sit at the top. Hundreds of other channels sit at the bottom.
Some producers now build brand placements into the film itself, because the ad share alone is thin. Techpoint’s own reporting warns that limited advertiser budgets and a crowded field could squeeze that route too.
The risk nobody prices in
YouTube pays in dollars. Producers spend in naira.
One of Nigeria’s best-known directors made the point in September. When people say a million views earns $10,000, he argued, it is because of the exchange rate. If the dollar fell to around ₦200, he said, many would leave YouTube. That is a warning, not a forecast. But it names a real exposure: a large part of the platform’s pull for local producers is currency, and currency is not something a producer controls.
The open register is not open everywhere
Most of the hard data in this piece is Nigerian. That is not because Nigeria is the whole story. It is because Nigeria is the market that gets measured. Ghana has no systematic box office tracking. Kenya’s film economy sits partly in movie shops selling titles at around KSh30 on flash drives, which no official statistic captures.
And the YouTube register has its own borders. YouTube’s Partner Programme covers only around a dozen African countries, including Nigeria, Kenya, Ghana, South Africa, Egypt, Morocco, Tanzania, Uganda, Zimbabwe, Tunisia and Algeria. Much of Francophone Africa is excluded. Senegal, Mali, Cameroon and the DRC cannot monetise, and Côte d’Ivoire is only partly covered.
For a filmmaker in Dakar or Kinshasa, the register that is “open to everyone” is not open to them.
Where it is open, it still does not guarantee a living. Ghana’s Kumawood producers moved to YouTube when cinemas shut during the pandemic, and some describe it as a survival option more than a fortune. A Ghanaian producer, on the platform’s economics, says actor fees often leave too little margin once production costs are covered.
How to read the three registers
No register wins on every measure. Cinema pays the largest cheques to the fewest people. YouTube pays the most producers, but modestly. Streaming sits between them, and is the least stable at the moment.
The producers doing best are not loyal to one. They match each film to the register that fits it. A film built for the big screen goes to cinema first. A film built for volume goes to YouTube. A film built for a platform’s catalogue goes to streaming, if a buyer still exists. The mistake is treating the registers as rivals.
The question underneath
Cinema is gated by capital, streaming by curation, and YouTube by geography and exchange rates. Each gate keeps a different group out.
So the useful test for any film is not “which platform pays most?” It is “which register can this film actually reach, and what does it cost to stay there?” For some producers, the honest answer is that only one of the three is within reach.
The industry’s next challenge is making more of them reachable.

Written by Layo
Lead Editorial Writer, Creative Brief Africa
Outside of her editorial work, she writes Curious Health, a newsletter focused on everyday health questions, explored with clarity and care.